Key takeaways
Joao Alves says Bleap's average customer is 38 years old, college-educated and upper class, and that its competitors are Trade Republic rather than Coinbase or Binance.
Bleap runs non-custodially on Arbitrum One, holds MiCA licensing for fiat-to-crypto conversion and offers dollar savings vaults that Alves says pay around eight to 9%.
Alves says 30% of retail customers used the savings vaults, with an average deposit of around $4,000.
Watch the episode

Summary
The former Revolut card lead says his DeFi-based neobank is winning older European savers who have never used Binance or Coinbase, and who do not know they are using crypto.
Bleap, the neobank founded by former Revolut card lead Joao Alves, is drawing customers who look nothing like the usual crypto crowd. Alves says the average user is 38 years old, college-educated and upper class. He names Trade Republic as a main competitor.
From Revolut to DeFi rails
Joao Alves spent around four years at Revolut building cards globally. He says traditional fintechs will never move onto decentralized infrastructure, citing the innovator's dilemma and the risk of competing against the moat they have built. His thesis is that a better fintech can be built on top of stablecoins or DeFi for retail customers.
Bleap runs non-custodially on Arbitrum One. Alves says not holding customer funds makes the company less risky from a regulator's point of view, so entering a new country looks more like payment service provider work than bank activity. Its MiCA licensing covers fiat-to-crypto conversion.
“I don't think you should outsource the integrations part...I really believe that everything else like on and off ramps...are going to become a commodity...The person with the best UX will win.”
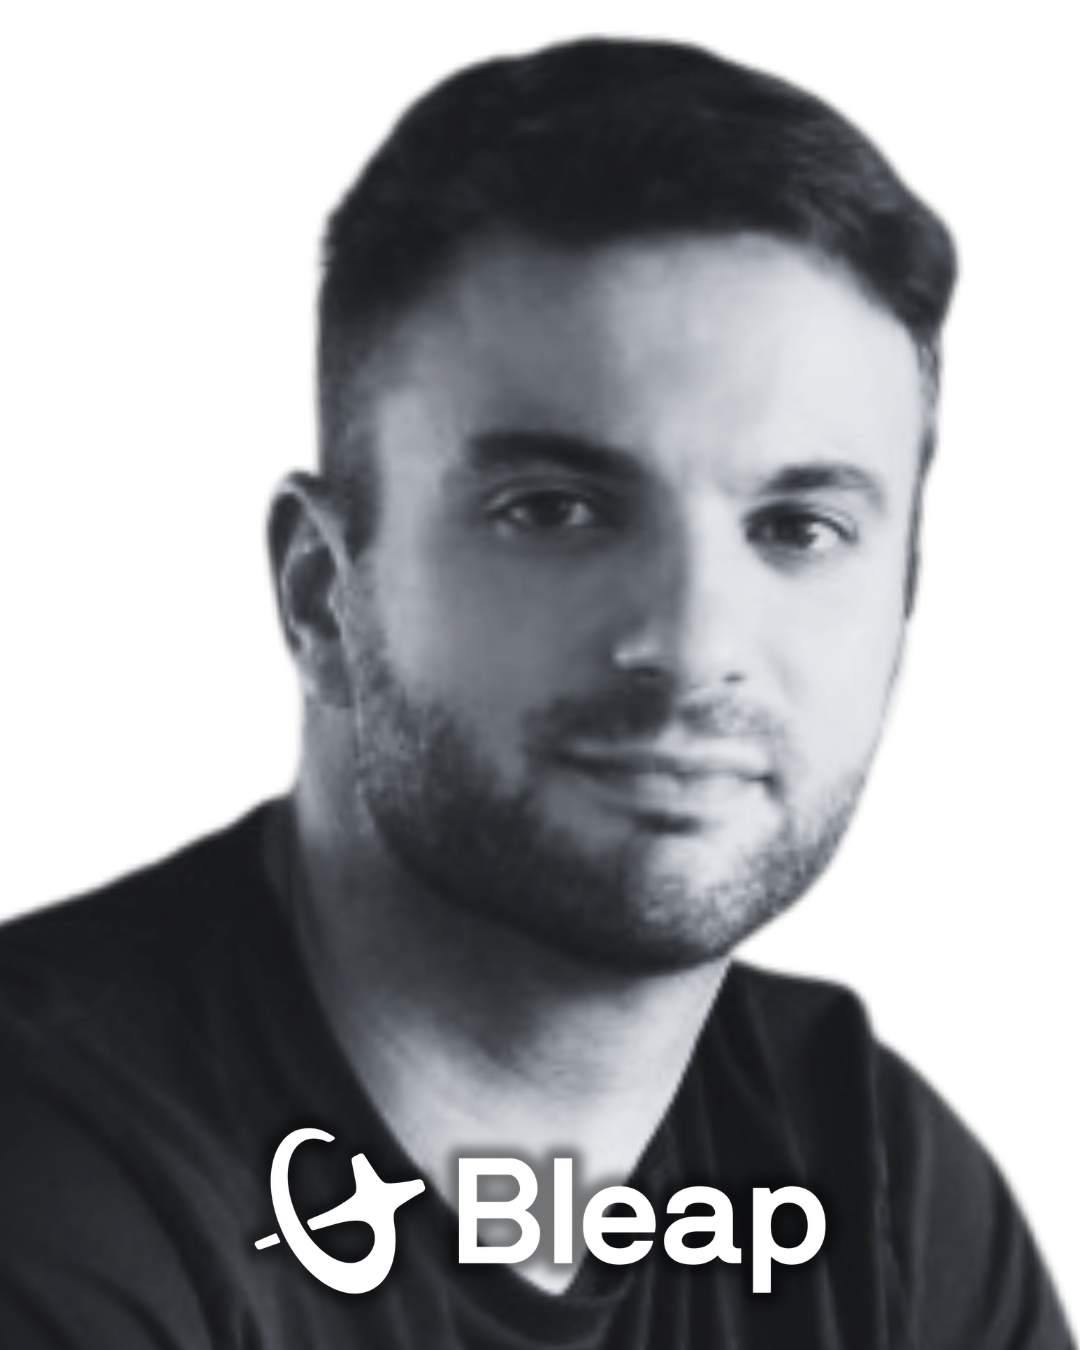 Joao Alves
Savings drive adoption
The company has relaunched its high-yield savings vaults, and Alves says the dollar vaults pay around eight to 9%. When the vaults were running before, 30% of retail customers used them, with an average deposit of around $4,000, and he calls them one of the main reasons people signed up. He was surprised that most users converted euros to USDC and accepted the FX exposure.
Crypto in the background
Alves says one balance works for DeFi, wallet transfers and card spending without the user knowing. Bleap charges no card fee and passes through the Mastercard rate, which he says is under 30 bips for major European currencies, maybe 20. It is adding currencies: it already has the euro and Mexican peso, and the Brazilian real is coming soon. Users can top up from MetaMask or Phantom from any chain.
What to build in-house
Joao Alves says outsourcing the risk engine was a mistake: during licensing it was hard to explain and needed many manual fixes. He argues integrations and wallet UX should never be outsourced, while on- and off-ramps will become commodities. Early on, he had to build ramps himself because no provider converted euros to a euro stablecoin instantly at a decent fee, and he says these now exist pretty much everywhere.
Alves's bet is that crypto rails can sit invisibly beneath a mainstream neobank. He finds it odd that crypto is commoditizing the core app experience, which in fintech was where companies set themselves apart. In his view, owning the wallet and the user experience is what will separate Bleap from players who only offer distribution.
Revolut, Mastercard, Coinbase, and MetaMask come up most.
- People
- Joao Alves
- Rob
- Companies
- Revolut
- Mastercard
- Coinbase
- MetaMask
- Trade Republic
- Dakota
- SWIFT
- Binance
- Phantom
- ARBA
- Cash App
- Moto
- Range
- Venmo
- Bleap
- Dfns
- dYdX
- Hyperliquid
- Visa Ventures


