Stabledash Live · · 36 min
a16z's Noah Levine Maps the New Stablecoin Stack: Charters, Credit, and the AI Mullet
With 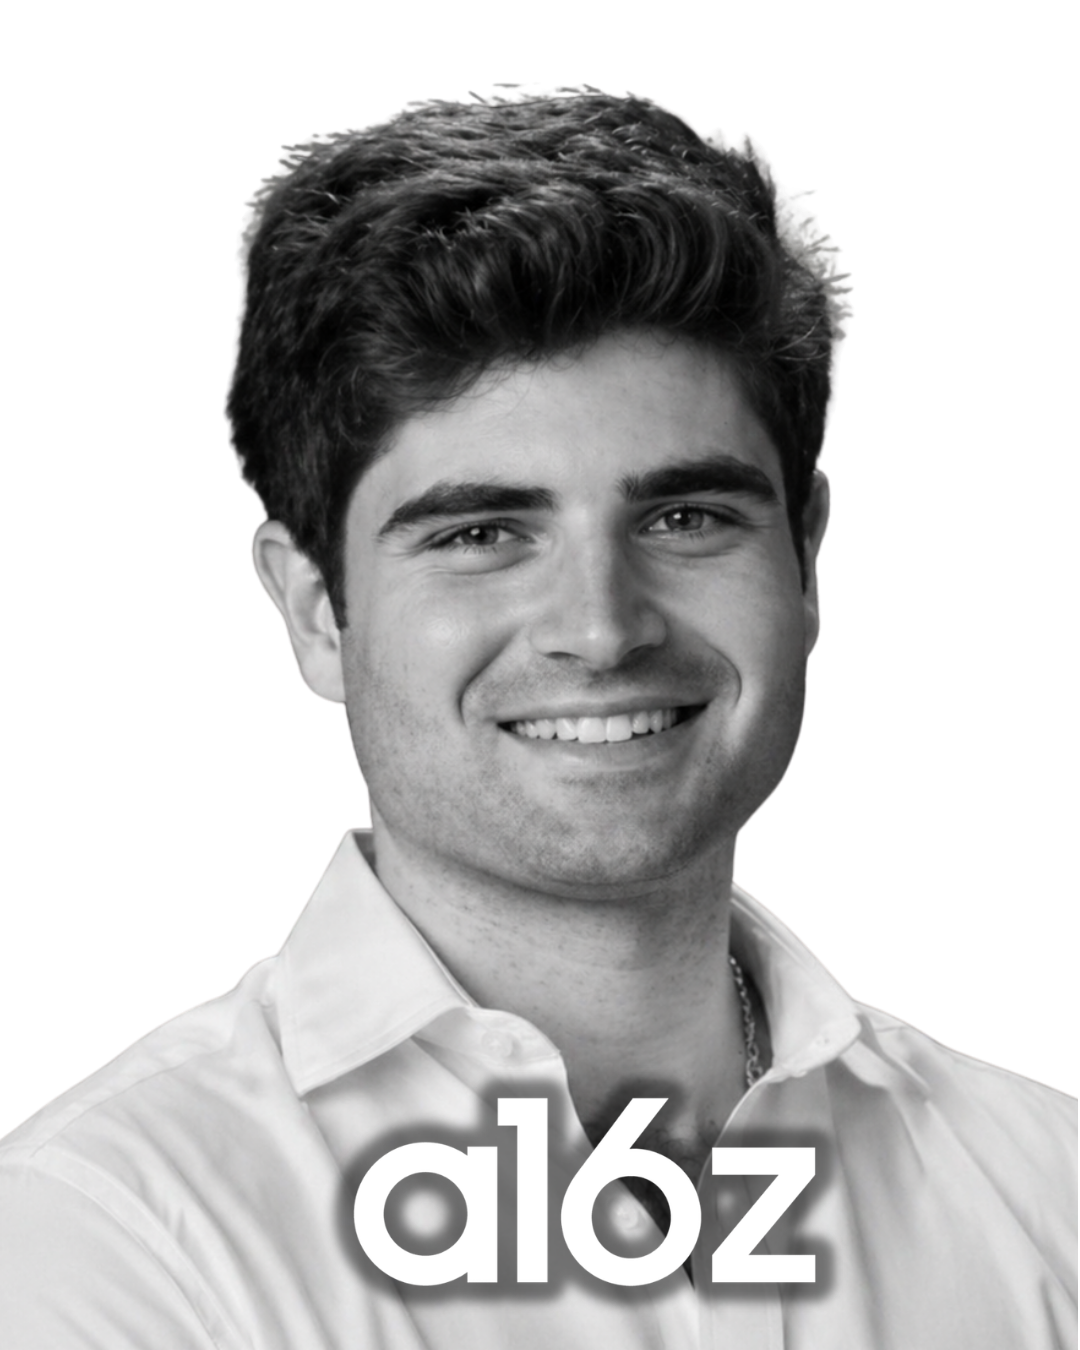 Noah Levine
Key takeaways
Noah Levine argues that stablecoins have become a better form of fintech and banking as a service, and that credit built on top of them matters more than payments.
He names bank connectivity and deep stablecoin-to-fiat FX liquidity as the main missing pieces of the stack.
He expects AI agents to buy from "headless merchants" over protocols like x4r2 and MPP, with cards in front and stablecoin settlement behind, a setup he calls the AI mullet.
Watch the episode

Summary
Levine lays out the barriers stablecoins have cleared, the infrastructure gaps still open, and how AI agents and cards fit into stablecoin settlement.
Noah Levine, who has been an investment partner at a16z crypto for the last three months, says stablecoins have grown into a better form of fintech and banking as a service. In his view, credit, not payments, is where their next phase will happen.
Barriers falling
Noah Levine names three core barriers to mainstream adoption: performance, regulatory clarity and privacy. He says the first is largely solved, recalling that buying an NFT in 2022 meant paying 20 or $30 of gas. On regulation, he points to the GENIUS Act and the Clarity Act as significant progress. Privacy has taken the longest, he says, though solutions are starting to appear.
He sees institutions picking chains for what they prioritize, with Tempo built for payments and Canton built around privacy. He adds that an OCC national trust charter could in future give issuers direct access to payment rails.
“I had stablecoins or I had some crypto asset in a a Phantom wallet, and I exported the keys and put it into a Solflare wallet. And, like, my balance just showed up... you can't take your keys from a Wells Fargo account and put it in the Bank of America.”
Noah LevineGaps in the stack
Stablecoins cut the time it takes to move money across borders, Noah Levine says, but larger transactions often get worse rates, so the market needs more liquidity providers between stablecoins and fiat. Banks run on legacy core ledgers that cannot simply plug into an API, and he expects middleware companies that close that gap to matter.
Credit and dollar access
Noah Levine argues that stablecoin-denominated accounts will create a new supply of dollars looking for productive use. In emerging markets, where credit is hard to get, he says smart contracts make onchain loan origination much more efficient. He finds the strongest product market fit outside the United States, in crypto capital markets and in dollar access. He also cites the Morpho integrations for borrowing against Bitcoin.
Agents and the AI mullet
Noah Levine expects buyers of developer services to shift from humans to agents. That would bring a class of headless merchants that compete on documentation, APIs and per-transaction pricing, reached over protocols like x4r2 and MPP. He describes stablecoins as digital cash for merchants who can set up and get paid instantly. He expects cards to join this ecosystem, with cards on the front for consumers and merchants settled in stablecoins.
For Noah Levine, the point is portability and use. He describes moving keys from a Phantom wallet to Solflare and seeing his balance appear, something a bank account cannot do. He says builders need to use the products themselves to form a real crypto strategy.
Tempo, Morpho, Bridge, and Coinbase come up most.
- People
- Noah Levine
- Anna
- Chris
- Drew Rogers
- Eric
- Kai Sheffield
- Nick
- Yuval
- Zach Abrams
- Zach Fowler
- Companies
- Tempo
- Morpho
- Bridge
- Coinbase
- Phantom
- Agora
- Stripe
- Mastercard
- Solflare
- Bank of America
- ClawCode
- CreditCoop
- Helox
- OpenAI
- OpenFX
- Perenna
- StableCore
- Stride
- Tesser
- Wells Fargo
- XFX
- Visa Ventures
- a16z crypto
- x4r2
- Circle
- Dfns